By Arthur R. van der Vant | Illinois Receiver
Inside the X Denver receivership: A $170 million loan default, a 455-unit apartment tower, and the operational responsibilities that follow a court-appointed change in control.
In commercial real estate, a loan default often makes the headlines. But the more consequential story begins after the default: What happens to the property, its operations, its income, and its future?
Who ensures that rent continues to be collected, essential services remain available, building systems are maintained, and reliable financial information is obtained? How does a court-supervised process help protect an asset while the parties navigate a financial and legal dispute?
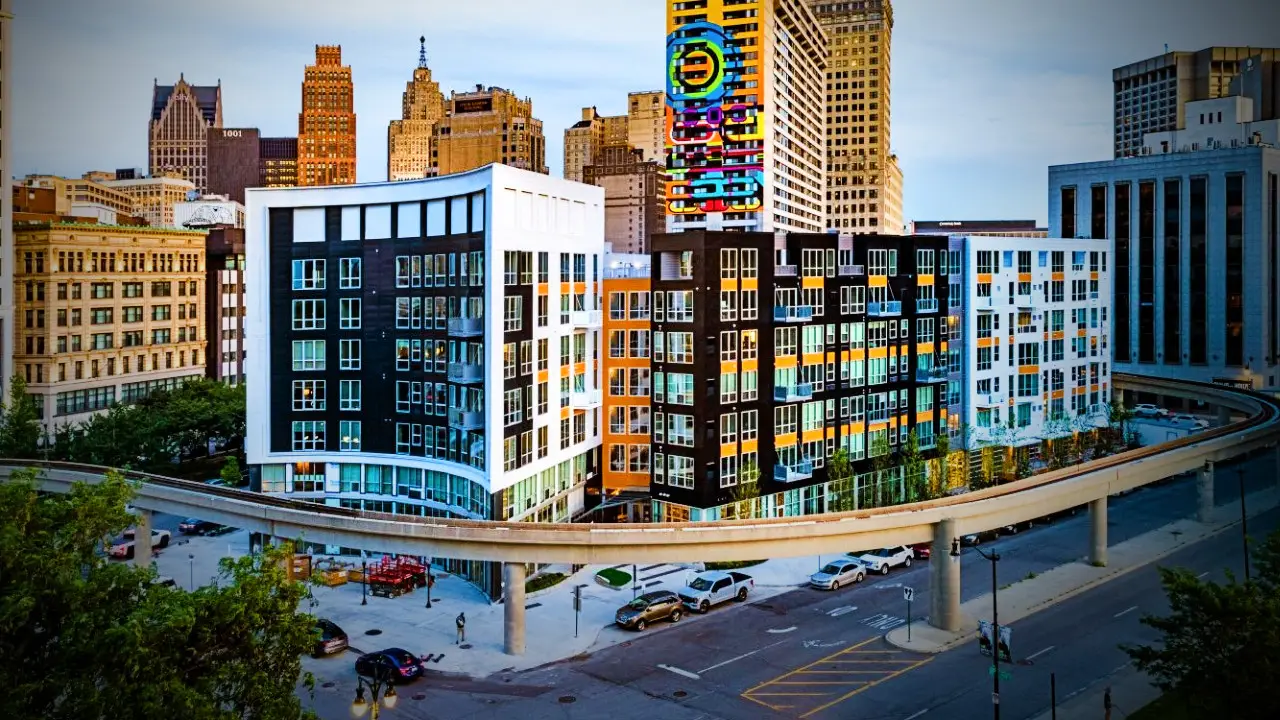
The recent receivership of X Denver, a 455-unit apartment complex near Coors Field in Denver, Colorado, offers a revealing case study.
The numbers are substantial: a 12-story residential tower, a reported $170 million loan, and a financing default that culminated in a court-appointed receiver in October 2026.
But the more important lesson extends beyond the loan balance. A receivership is not simply about taking control of a distressed property. It is about establishing the oversight, information, and operational discipline needed to protect the asset and support informed decisions about its future.
Inside the deal. The property behind the headlines
X Denver is located at 3000 and 3100 Inca Street, between Coors Field and Interstate 25. The property opened in 2021 and combines conventional apartment rentals with a co-living model in which residents can rent individual bedrooms in partially furnished apartments with shared living spaces.
Its amenities include outdoor decks with a heated swimming pool, tanning pool and hot tub, as well as fitness facilities and meeting spaces.
The property’s operating model is worth understanding. This is not simply a collection of conventional apartments. It combines residential leasing, shared amenities, and a co-living component, creating multiple operational considerations for whoever is responsible for managing the asset.
According to the Denver Business Journal’s October 12, 2026, reporting, the property had 30 units listed as available and 22 co-living slots on offer at that time. Advertised monthly rents included $949 for co-living rooms, $1,350 for studios, and $2,800 for a listed three-bedroom unit.
These figures are a snapshot of reported availability and asking rents, not a verified occupancy rate, actual collected rent, or complete picture of operating performance. Nevertheless, they illustrate why a receiver needs current leasing information and reliable operating data before assessing a property’s financial position.
The real estate itself must be evaluated separately from the debt secured against it.
The financing history. From land acquisition to loan default
The history of X Denver provides important context for the receivership.
Public records cited in the reporting show that the development site was acquired in 2017 through two transactions: one for $6.9 million and another for $3.19 million, totaling approximately $10.09 million.
The project opened in 2021. In January 2022, a $170 million loan was originated through two borrower entities: ENR Denver Investment LLC and ENR Denver Investment 2.0 LLC.
The lender identified in the reporting was CMTG JP Finance LLC, associated with Mack Real Estate Group. Mack Real Estate Credit Strategies is identified in the recorded financing documents.
The loan matured in January 2025. According to the lender’s complaint as described by the Denver Business Journal, the required outstanding principal, accrued interest, and other amounts due under the loan documents were not paid.
That is the central financial event underlying the receivership.
There is another significant piece of context. In May 2025, Newmark was reportedly engaged to market approximately $325 million in nonperforming debt associated with X Denver and the developer’s Phoenix counterpart. The reported amounts were $170 million tied to Denver and $155 million tied to Phoenix.
That figure represents the reported face amount of debt being marketed, not a verified sale price for either the debt or the real estate.
The distinction is important. Loan balances, the value of the underlying collateral, and the amount ultimately recoverable by a lender are different measures. The available reporting does not establish X Denver’s current market value or the eventual recovery on the loan.
The reporting also contains a relevant ownership and management nuance: The X Company, the Chicago-based developer associated with the project, told BusinessDen in 2024 that it had not been associated with the building or its management for some time. The borrower entities’ association with the developer’s address and the property’s development history should therefore not be treated as proof of who was actively managing the building immediately before the receivership.
For a receiver, establishing the actual ownership, management, contractual, and operational relationships is part of understanding the asset.
The receivership chronology. How the case unfolded
The path from loan maturity to court-appointed oversight did not happen overnight.
2017 – Land acquisition. The development site was acquired in two reported transactions totaling approximately $10.09 million.
2021 – Property opens. X Denver begins operating as a 455-unit residential property with conventional rental and co-living options.
January 2022 – Financing established. The $170 million loan is originated through ENR Denver Investment LLC and ENR Denver Investment 2.0 LLC.
January 2025 – Loan maturity. The loan reaches maturity, and the lender subsequently alleges that the required amounts remain unpaid.
May 2025 – Debt marketed. Newmark is reportedly engaged to market approximately $325 million in nonperforming debt associated with the Denver and Phoenix projects.
September 2026 – Receiver requested. The lender seeks court-supervised intervention for X Denver.
October 9, 2026 – Receiver appointed. Denver District Court Judge Heidi Kutcher appoints a receiver.
According to the Denver Business Journal, X Denver representatives did not appear at the October 9 hearing or submit a response to the lender’s complaint. That is a reported procedural fact, not a basis for drawing conclusions about the parties’ motives or the ultimate merits of every disputed issue.
The court’s stated concern, as reported by the publication, was that the property and its rents, revenues, income, and other benefits were at risk of impairment or loss.
The appointment placed the property under the authority of a court-appointed receiver while the broader financial and legal issues remained unresolved.
The operational details that matter most
For those of us who work in real estate receivership, one of the most revealing aspects of this case is not the size of the loan. It is the emphasis on access to the property, records, and operational information.
The Denver Business Journal reported that the court order required the company to provide access to the property and deliver current leases, insurance information, tax documents, and other records within three business days. The order also addressed the provision of information explaining building operations, with a 30- to 60-day timeline for that communication.
The receiver was also required to submit reports to the court every three months. According to the reporting, the order authorized the receiver to list and sell the property with Mack’s approval.
These details illustrate several practical priorities.
First, establish access and understand the property. A receiver needs a reliable picture of the physical asset, its building systems, maintenance requirements, leases, service providers, and immediate operational obligations.
Second, establish financial visibility. Current rent rolls, collections, outstanding balances, operating expenses, contractual commitments, insurance, and property-tax information are essential to understanding the property’s financial condition.
Third, maintain continuity. Residential properties cannot simply pause operations while financial and legal matters are resolved. Residents still require functioning building systems, maintenance, essential services, and clear communication.
Fourth, establish accountability. Accurate records and regular reporting support the court-supervised process and provide a documented basis for evaluating the property’s condition and the receiver’s actions.
These are general operational priorities, not assertions that specific deficiencies existed at X Denver. The appointment order and published reports provide a basis for discussing the receiver’s responsibilities, but they do not independently establish the property’s current cash flow, physical condition, or occupancy performance.
Preserving real estate value
A $170 million loan is a significant financial obligation. It is not, by itself, a valuation of the underlying property.
The value of a multifamily asset depends on a wider set of considerations: its income-producing capacity, occupancy, rental collections, operating expenses, physical condition, capital requirements, market position, and the financing environment.
For a 455-unit building such as X Denver, those considerations must be understood together.
A property can be relatively new and offer substantial amenities while still facing serious financing challenges. Conversely, a loan default does not automatically establish that the underlying real estate has lost its utility or that a sale is the only viable outcome.
The receiver’s work is to operate within the authority granted by the court, understand the asset’s actual circumstances, and support appropriate decisions based on reliable information.
Depending on the facts, possible paths may include continued operation, operational stabilization, restructuring, or a sale where authorized and appropriate. None should be assumed before the relevant financial, operational, and legal circumstances have been evaluated.
The immediate task is to replace uncertainty with a clearer understanding of the property.
Five lessons for real estate owners, lenders, and attorneys
The X Denver case offers several practical lessons for the broader commercial real estate community.
1. Prepare for loan maturity well before the deadline.
Refinancing, capital needs, lender communications, and contingency planning should receive attention well before a loan matures. Early preparation gives stakeholders more time to understand their options and address problems before they become acute.
2. Treat operational information as an essential asset.
Leases, financial statements, insurance records, vendor contracts, maintenance logs, and property-management information are not merely administrative documents. They are fundamental to continuity and informed decision-making, especially during a change in control.
3. Distinguish the property’s condition from its financing position.
A defaulted loan and a distressed property are related concepts, but they are not identical. Understanding the asset requires an independent assessment of its operations, physical condition, income, expenses, and market circumstances.
4. Recognize that a transition in control requires execution.
Court authority must be translated into practical management. Property access, records transfer, cash-flow oversight, vendor coordination, maintenance, and resident communications all require appropriate attention.
5. Preserve options through disciplined oversight.
Stabilization, continued management, restructuring, and disposition are not interchangeable decisions. Reliable information and compliance with the court’s directions help create a sounder basis for determining what should happen next.
Beyond the default
The X Denver receivership is a timely example of the intersection between real estate finance, property operations, and court-supervised oversight.
Its 455 residential units, co-living model, $170 million loan, and financing history make it a substantial case study. But the underlying lesson applies to distressed real estate more broadly.
When a receiver is appointed, the work extends beyond the immediate loan dispute. It involves understanding the property, establishing reliable information, maintaining appropriate operations, documenting decisions, and acting within the authority granted by the court.
The receiver’s appointment does not predetermine whether the property will ultimately be sold, refinanced, or continue operating under a different arrangement. It establishes a framework for managing the asset while those questions are addressed.
For owners, lenders, attorneys, investors, and property professionals, the central lesson is straightforward:
Preserving real estate value begins with understanding the asset, protecting its operations, and making the next decision on a sound factual foundation.
That is the work that begins beyond the default.
Arthur R. van der Vant
Illinois Receiver
312-607-4646
vandervant@illinoisreceiver.com
#CommercialRealEstate #Receivership #IllinoisReceiver #PropertyManagement #RealEstateLaw #DistressedRealEstate #CommercialLitigation #Banking #RealEstateFinance #ChicagoRealEstate #IllinoisLaw #Workout